Track the evidence behind your building improvements
Keep the evidence behind each improvement clear. Connect the baseline, approved measure and performance record so your team can understand what changed and how savings are assessed.
Start with your property details. Robert will help you evaluate the scope and next step. Prefer to talk? Book with Robert.
Keep the decision and its evidence together
The AssetMax Record brings source information, approvals, implementation dates and measured performance into a property history that finance and facilities teams can revisit.
Trace a measure through the record
The record links each stage of the measure, keeping projected opportunities distinct from implemented work and verified outcomes.
AssetMax Record · documentation structure
Source and finding
Records, reporting period, assumptions and the question being evaluated.
Approval and scope
The client decision, agreed work and responsible parties.
Implementation date
What changed, when it changed and the supporting delivery record.
Verification
Baseline, method, measurement period and relevant operating changes.
Each entry relates to its source records, property and measure.
Track the bill and the building performance
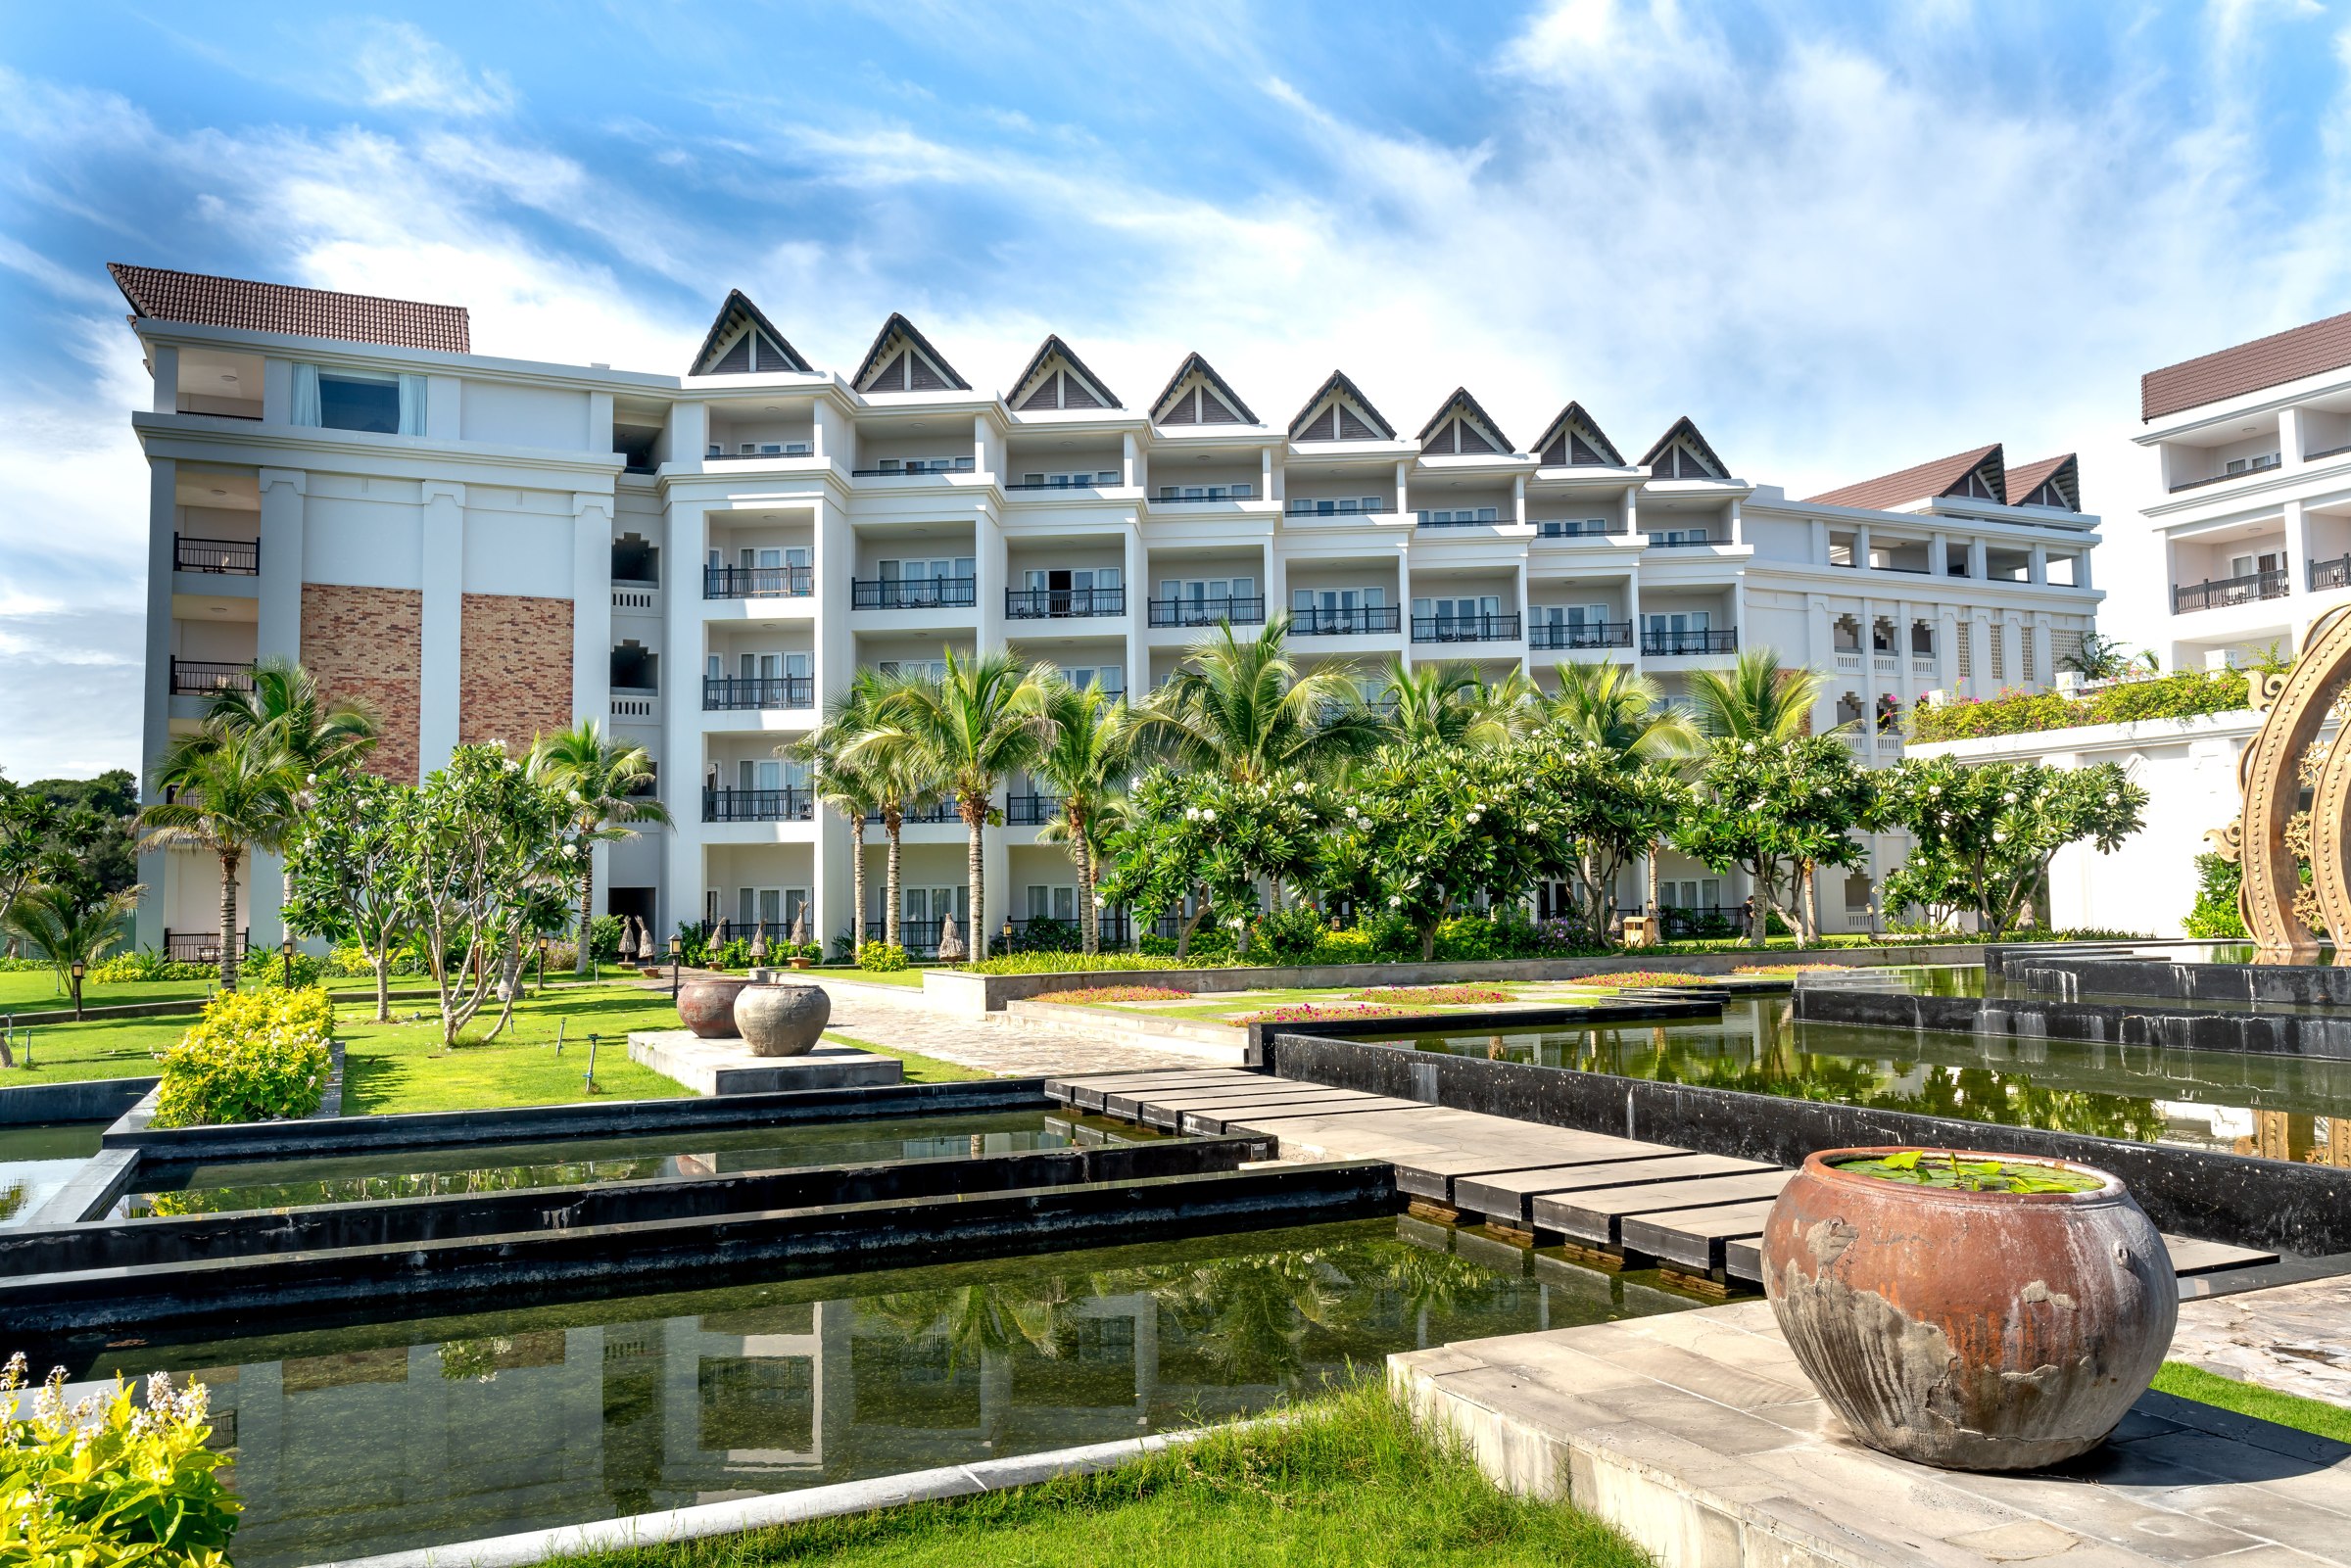
This hotel case study distinguishes water-bill savings from the change in water consumption, giving the operating result useful context.
average water-bill savings reported by the hotel
Explore the resultUnderstand what changed
Distinguish one-time recoveries from recurring savings. Keep implementation costs and material assumptions with the performance figures so later decisions have the necessary context.
Make the evidence useful to your team
Bring the findings, decisions and supporting records into a clear property-level account. Use it to understand the work completed, the measurement period and the assumptions behind reported performance.
Before you decide
What makes a saving verified?
Verified Savings are measured against the agreed baseline using the arrangements in the governing agreements. The record identifies the implemented measure, comparison period, assumptions and relevant operating changes.
Can the sample report be shared internally?
Yes. The public illustrative sample and executive brief are designed to support evaluation and internal discussion. They contain no real client financial information. Actual engagement findings are subject to the confidentiality provisions and sharing permissions in the applicable documents.
Request a free savings assessment
Tell Robert where costs are putting pressure on your properties. Start a focused conversation about the savings and improvements worth investigating.
- Discuss your priorities and the right review scope
- Understand the findings, responsibilities and fees
- Agree the next step for your property or portfolio
Your property details are enough to start. Audit documents follow through the agreed private process.
Book with Robert